- Home
- Roof Insurance Claim Assistance
Roof Insurance Claim Assistance in South Fulton, GA
A claim is a record problem before it is a money problem. The adjuster sees the roof once, often weeks after the storm. What the owner can show decides how much of the damage is understood. In South Fulton, GA, storms hit in every season, and a roof may carry wear from several events. Our job on a claim is narrow and practical. We document what the roof shows, date what can be dated, separate storm damage from wear, and write a repair scope the adjuster can read line by line. We do not decide coverage. The policy and the carrier do.
Building use: whose claim it is
Commercial claims come from several seats. A property manager on Old National Highway may hold a policy for a multi-tenant strip. A logistics owner by the Fulton Industrial District may carry a business-interruption rider on top of the property policy. A GC may be managing a repair on behalf of an owner who is out of state.
Each seat needs different paper. The manager needs tenant impact. The logistics owner needs downtime dates. The GC needs a scope that matches the carrier's estimate item by item. We build the file to serve all three, from one set of photographs and one roof zone map.
Roof mechanism: what separates storm damage from wear
Carriers pay for sudden damage. They do not pay for age, neglect or long-term wear. The line between them is often thin on a roof. A split seam may come from wind or from years of heat cycling. A lifted edge may come from one gust or from fasteners that were already backing out.
The evidence sits in the pattern. Wind damage lines up with exposure: corners, windward edges, one side of the building. Hail leaves impact marks in a random scatter across all faces. Wear shows as uniform crazing, chalking and shrinkage. Prior repair patches show in different materials. We map each finding to a roof zone and note which pattern it fits. That map lets the adjuster see the reasoning, not just the conclusion.
Heat adds a complication. Summers here run long and humid, with Atlanta passing 95°F on roughly seven days a year. Sealants and thin membranes age in that heat, so a roof can look worn even when a storm did the real harm. We record the pre-storm condition from past inspections, maintenance logs and older photographs wherever they exist. That baseline lets the adjuster separate the storm's share from the sun's.
Inspection findings: the claim file
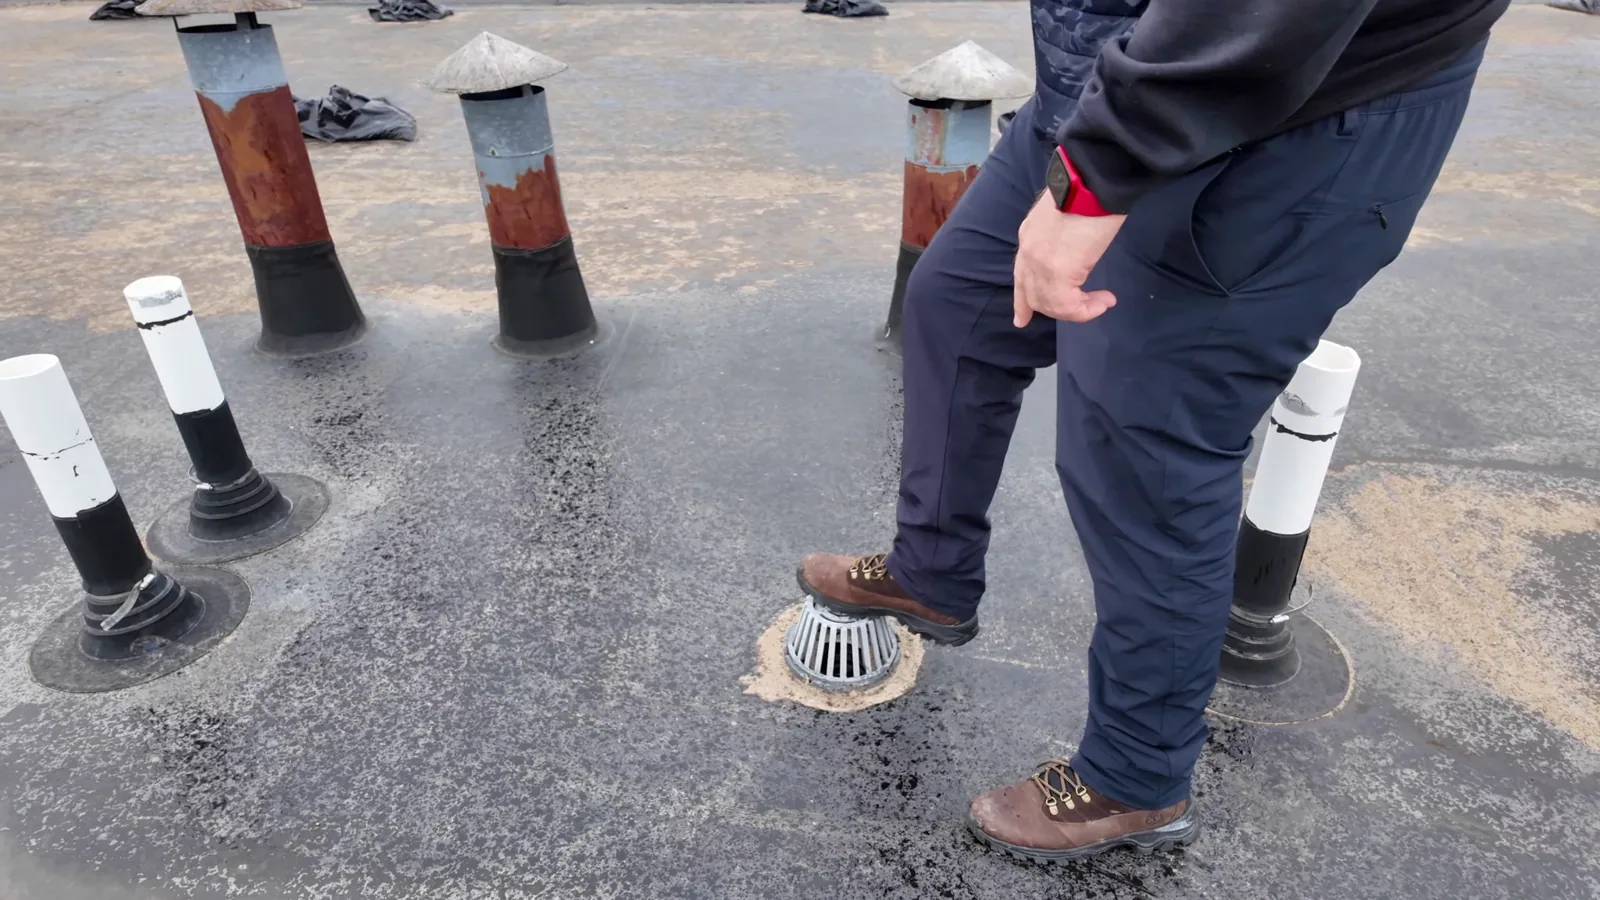
The file starts at the first visit. It holds dated wide shots of each roof zone, close shots of each defect with a scale marker, and interior photographs matched to roof locations. It records the weather on the day, the time of discovery and who reported it. It lists every temporary measure taken and its cost.
Test openings add proof. A cut at a suspect area shows whether insulation is wet and whether the wetting is recent. A drone survey shows the roof as a whole, which helps on large decks. For hail, we test for bruising and note counts per test square. All of it is stored by zone and date. A roof condition report pulls it into one document the adjuster can open in one sitting.
Interior evidence matters as much as roof evidence. Stained ceiling tiles, wet insulation fallen from a grid, rusted fixtures and damp stock all go into the file with dates. We match each interior location to the roof zone above it. If water traveled along a duct or a beam before dripping, the note says so, so the roof source is not guessed from the stain.
Scope options: itemize, separate, price
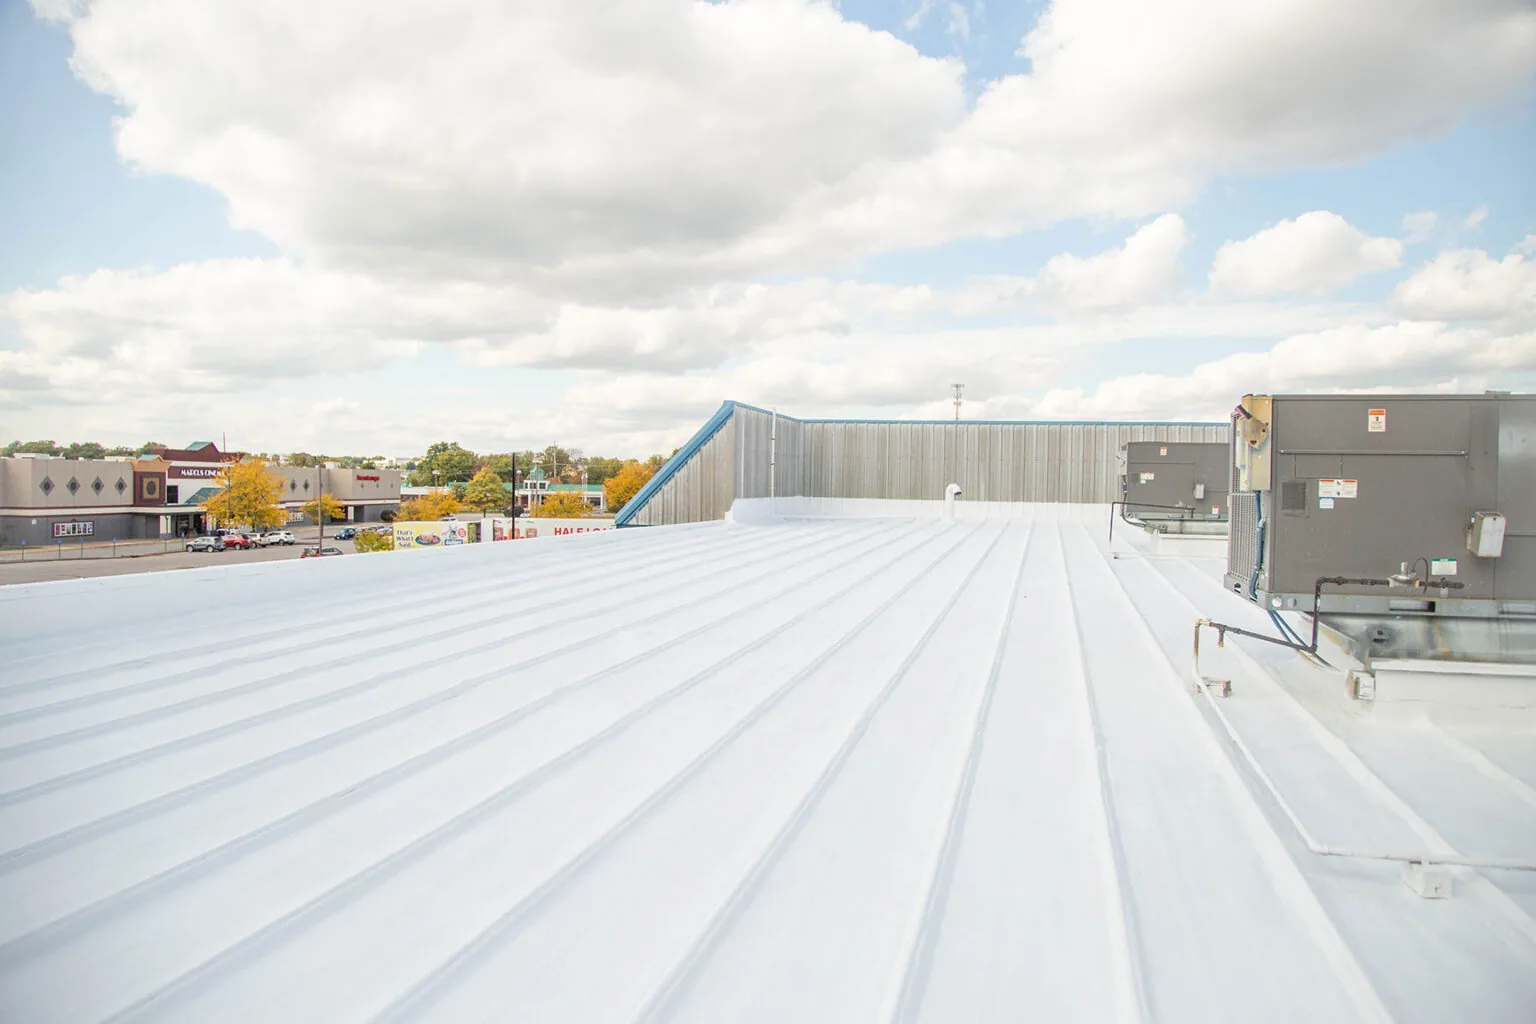
The repair scope is written to line up with the estimate. Each item has a roof zone, a quantity, a method and a price. Emergency work sits in its own section, flagged as temporary. Permanent repair sits in another. Items that are wear or upgrade, not storm, sit in a third, so the carrier is not asked to pay for them and the owner knows what falls outside.
Code items need care. Two code editions matter here: the 2024 IBC with Georgia Amendments, effective in the city on January 1, 2026, and the state's mandatory 2015 IECC energy code. When a repair triggers a code requirement, such as added insulation, the scope names the requirement and its source. Whether the policy pays for it is a policy question. We make the item visible so it can be discussed.
Access and sequencing: protect the evidence, protect the building
Two clocks run at once. The building cannot stay open to water, and the adjuster needs to see the damage. We resolve this by documenting first, then securing. The first visit photographs the opening and the surrounding zones, takes core samples if needed, and then places the dry-in. Removed materials are bagged, labeled by zone and kept for the adjuster's visit.
When the adjuster arrives, we walk the roof with them, show the zone map and open the test cuts. The GC gets a copy of every note. Permanent work waits for approval, unless further delay would cause more damage. In that case we document the added risk, proceed with a narrow repair and keep the record.
Tenant impact is tracked in the same file. The property manager lists affected suites, closure dates and any relocation costs, and the roof scope references the same zone numbers. A single map ties the roof, the interior and the business loss together, which keeps three separate conversations from contradicting each other.
Timing: dating the event
Dates matter. Regional records list damaging winds in every month, roughly nineteen such days a year, and large hail on about seven days with an April peak. Tornadoes can occur at any time, most often in March through May. A claim file that names the storm date, the observed damage and the first-notice date reads cleanly. One that cannot date the event invites questions.
We encourage owners to report damage promptly and to keep photographs from before the storm if they exist. Past inspection records and the maintenance log help show the roof's condition before the event. For hail, the hail damage repair evidence includes test-square counts. After a major event, the storm damage repair record carries the temporary and permanent work in one place.
Send the storm date and the policy contact
Should we call the roofer or the insurer first?
Call both, in this order: secure the building, then notify the carrier. Water does not wait for a claim number. Photographs taken before any temporary repair become the baseline, so we capture them at the first visit. The carrier's notice deadlines are in the policy, and the owner or broker handles them. We keep the dated record.
Do you negotiate the claim with the adjuster?
We document, explain and coordinate. We walk the roof with the adjuster, show the evidence and answer questions about methods and quantities. We do not decide coverage, and we do not promise an outcome. A clear scope with test results tends to shorten disputes, because the disagreement narrows to price instead of facts.
What if the carrier's estimate is lower than our scope?
We compare line by line. Differences usually fall into quantity, method or an item the estimate omitted. We send the carrier the evidence behind each difference, such as a test cut or a photograph. If the gap remains, the owner decides how to proceed, and we can phase the work so critical items go first.
Will repairs wait for the settlement?
Emergency protection does not wait. The temporary dry-in goes on at once and is documented. Permanent work waits for approval where possible, but a roof that is still taking water may need a narrow permanent repair first. We record why, so the carrier sees the reason.